Name/Title
IRS Letter March 20,1953 Exempt from Federal Income Tax pg3Entry/Object ID
001693Tags
Robert McLeod Jackson, William Bull, Sarah WellsScope and Content
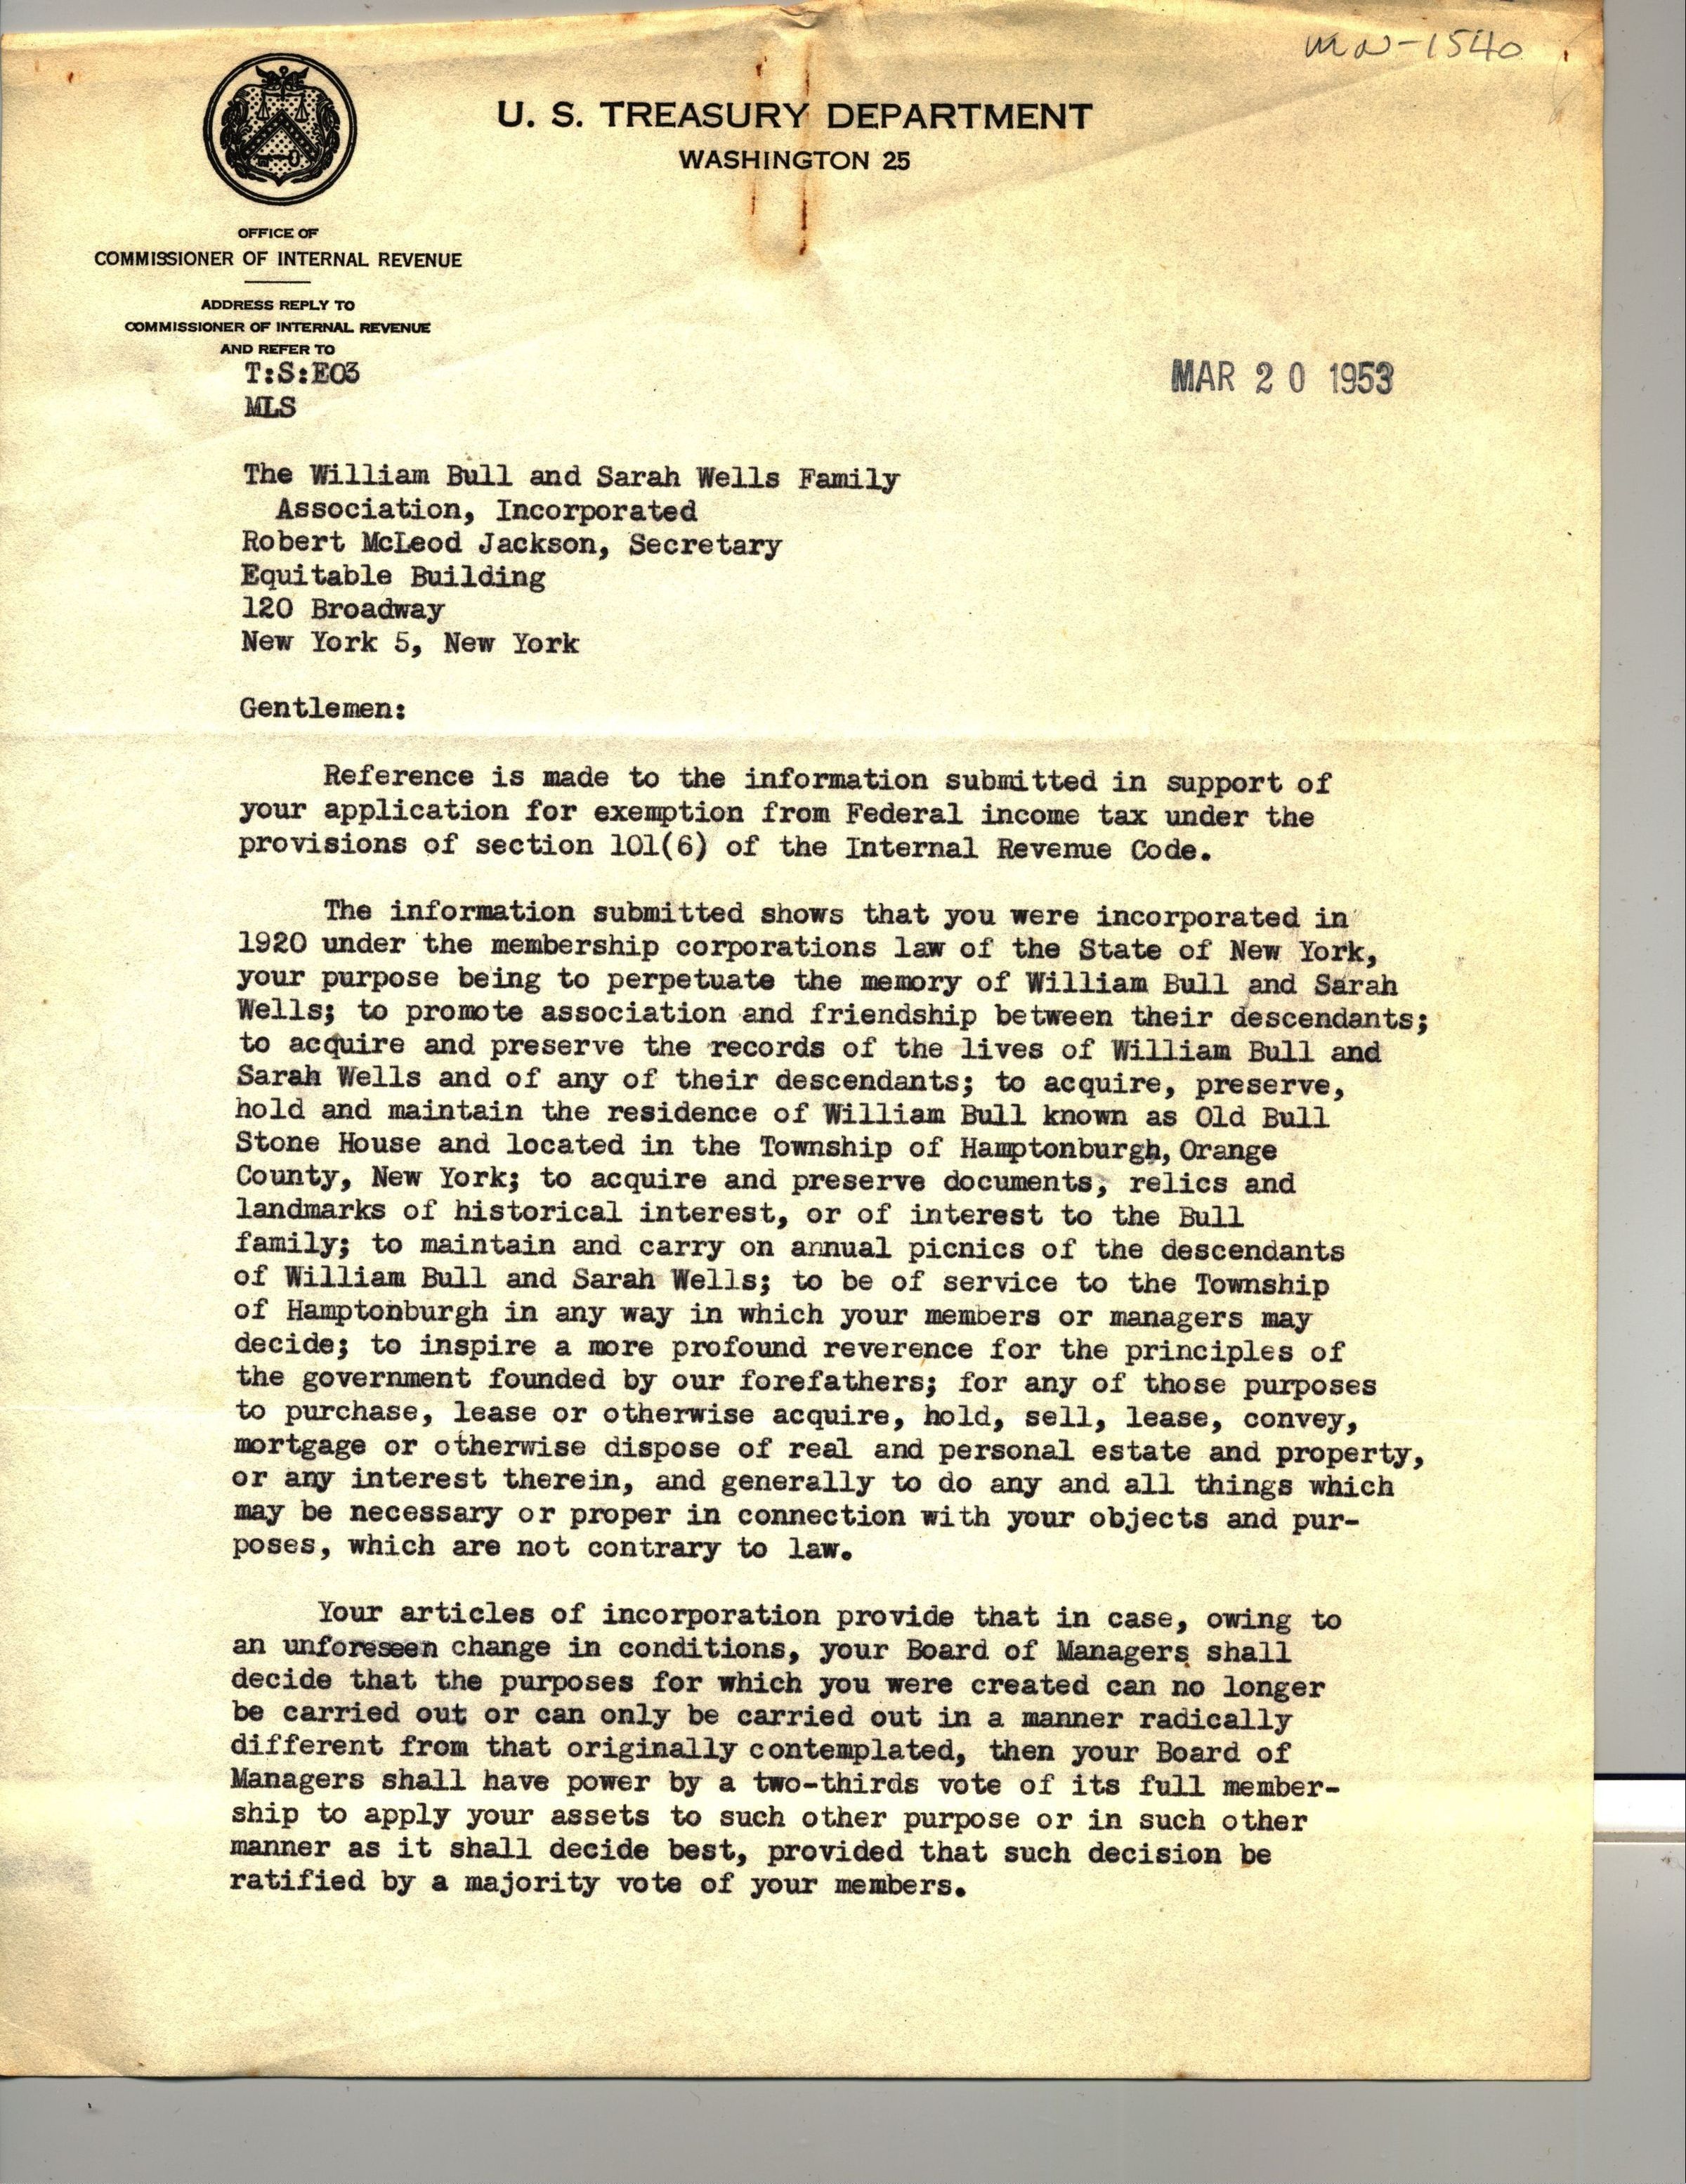
This correspondence is a formal determination letter from the U.S. Treasury Department, dated March 20, 1953, regarding the tax-exempt status of The William Bull and Sarah Wells Family Association, Incorporated.
Here is a summary of the key points:
The Request
The Association applied for federal income tax exemption under Section 101(6) of the Internal Revenue Code. This section typically covers organizations operated exclusively for religious, charitable, scientific, literary, or educational purposes.
Organization & Activities
The documents outline the Association’s background and operations:
Purpose: Formed in 1920 to preserve the memory of William Bull and Sarah Wells, maintain their "Old Bull Stone House" in Hamptonburgh, NY, and preserve family documents and relics.
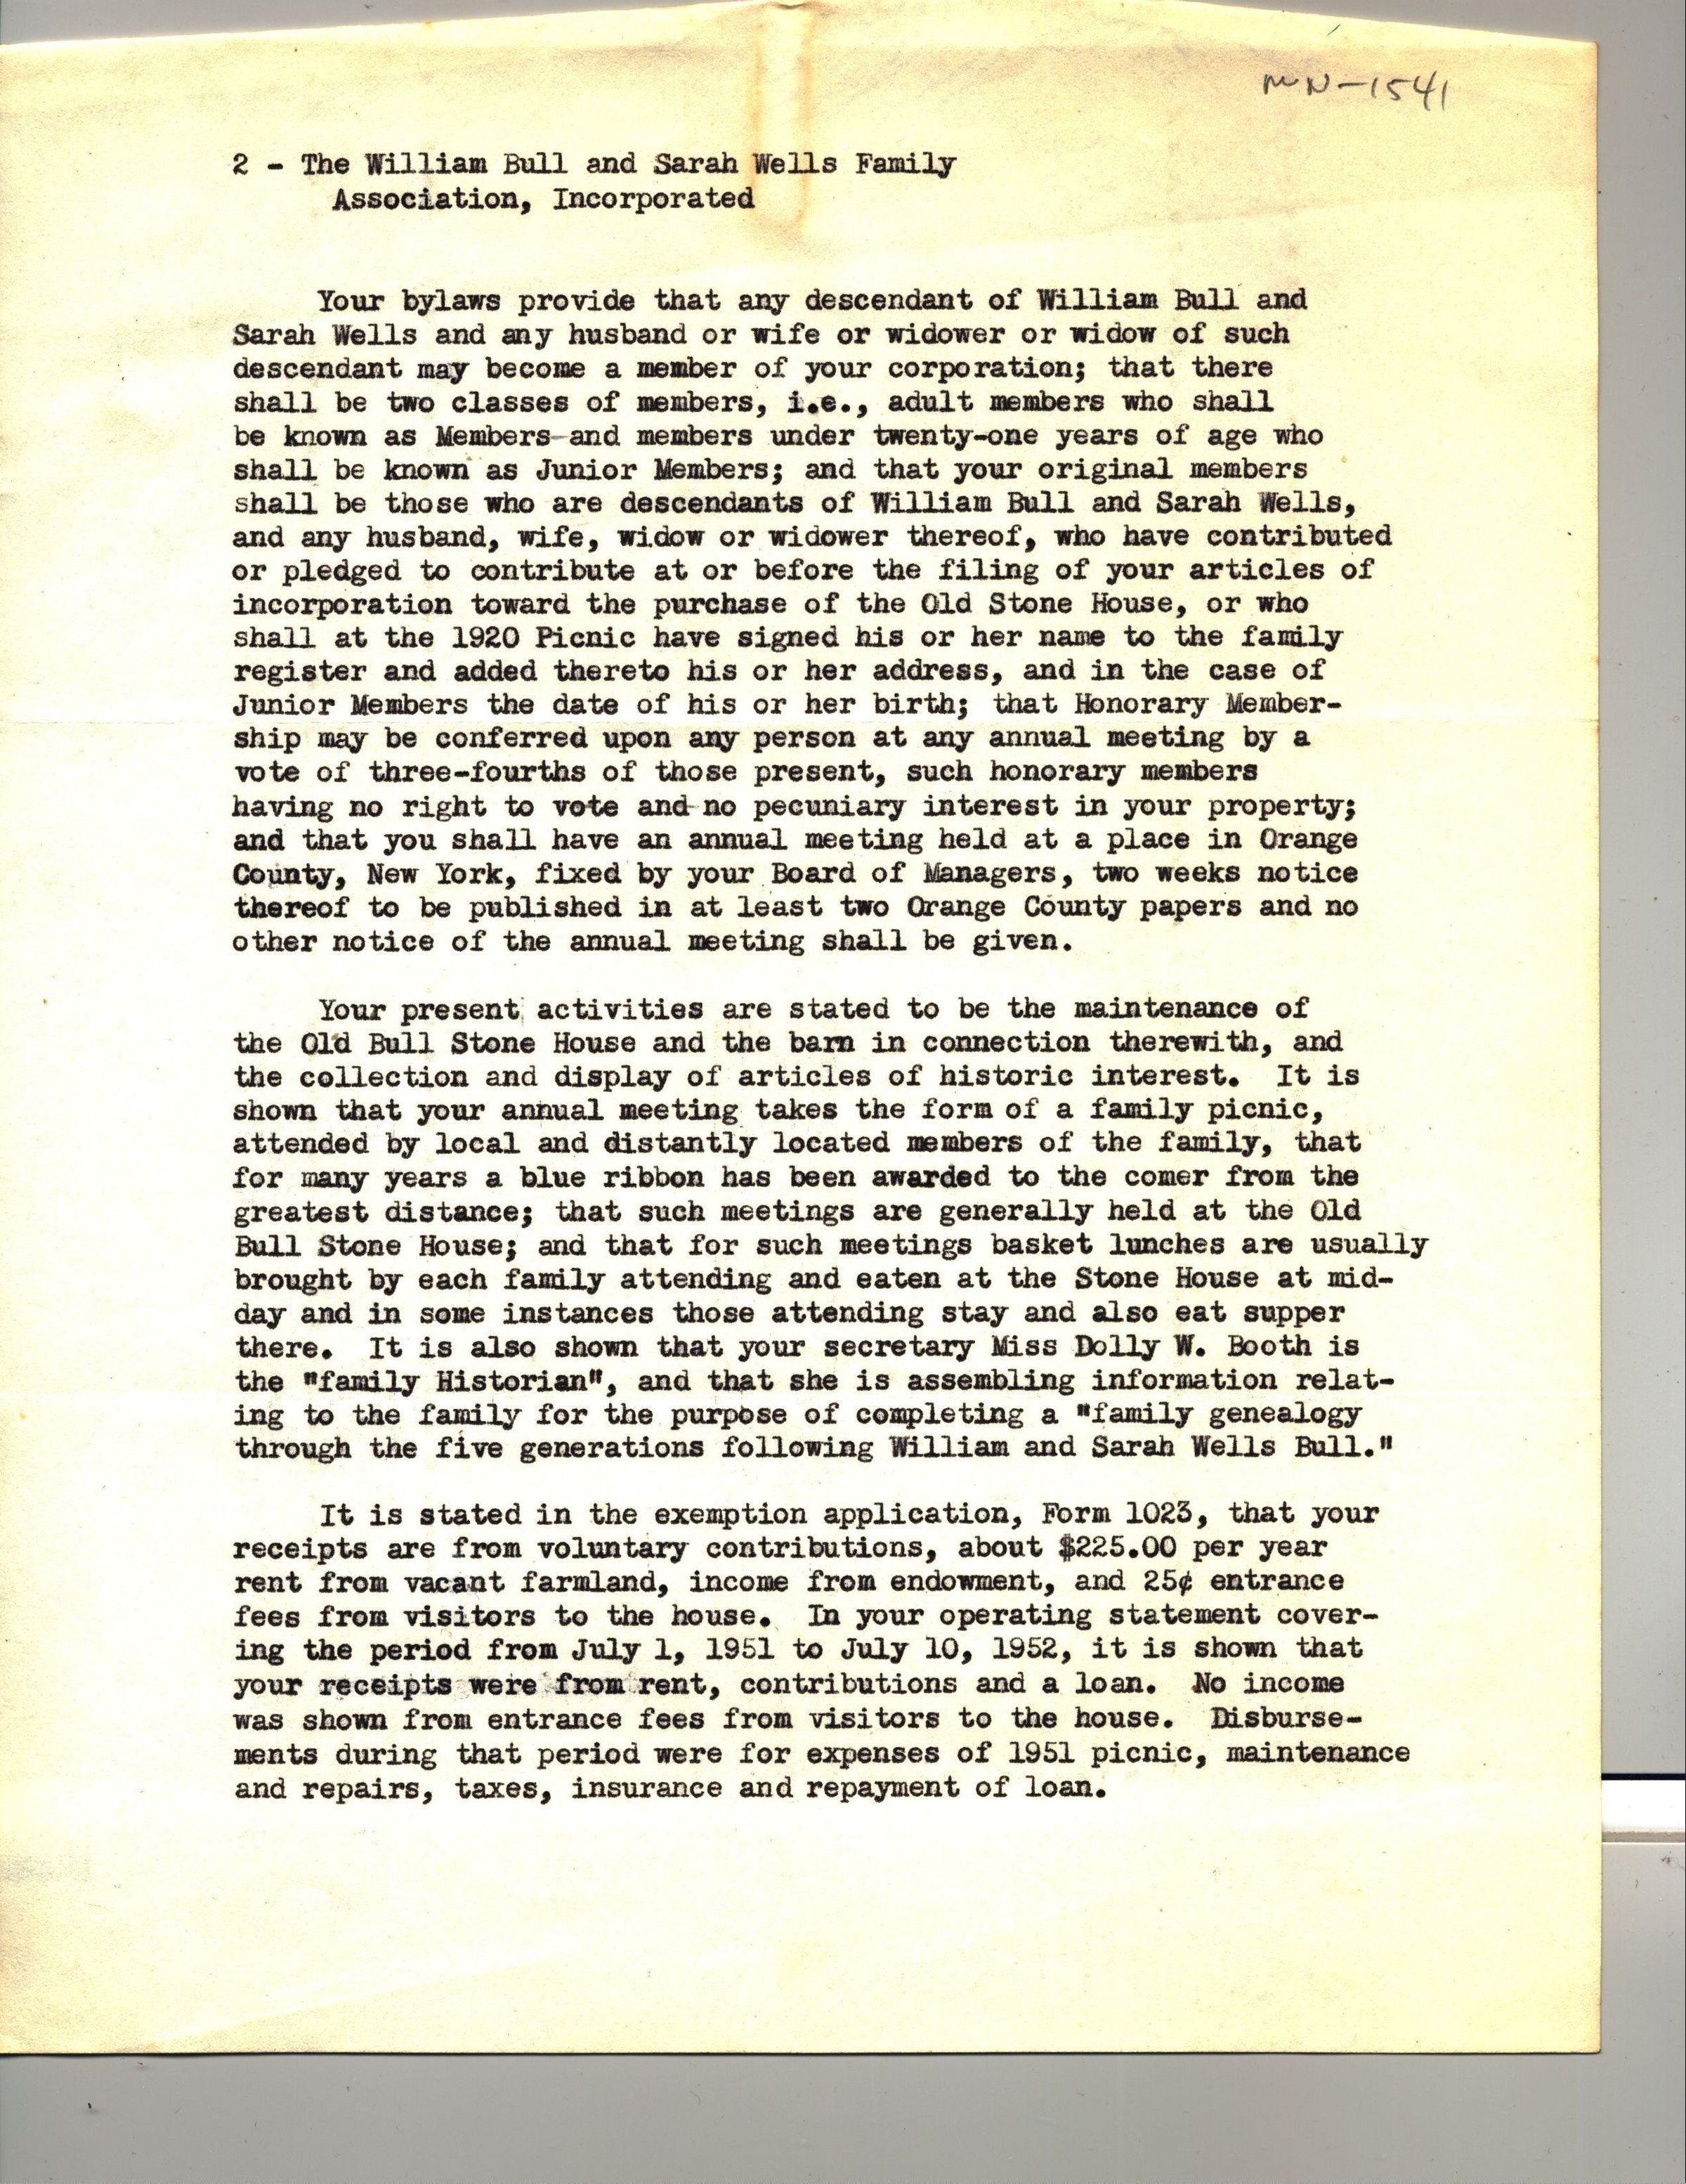
Membership: Open to descendants of the couple and their spouses.
Activities: Annual family picnics and meetings at the homestead, awarding "blue ribbons" for long-distance travel, and maintaining a family genealogy (managed by "family historian" Miss Dolly W. Booth).
Finances: Income was derived from voluntary contributions, farmland rent, and a 25-cent entrance fee for visitors (though no visitor income was reported in the 1951-1952 period).
The IRS Ruling
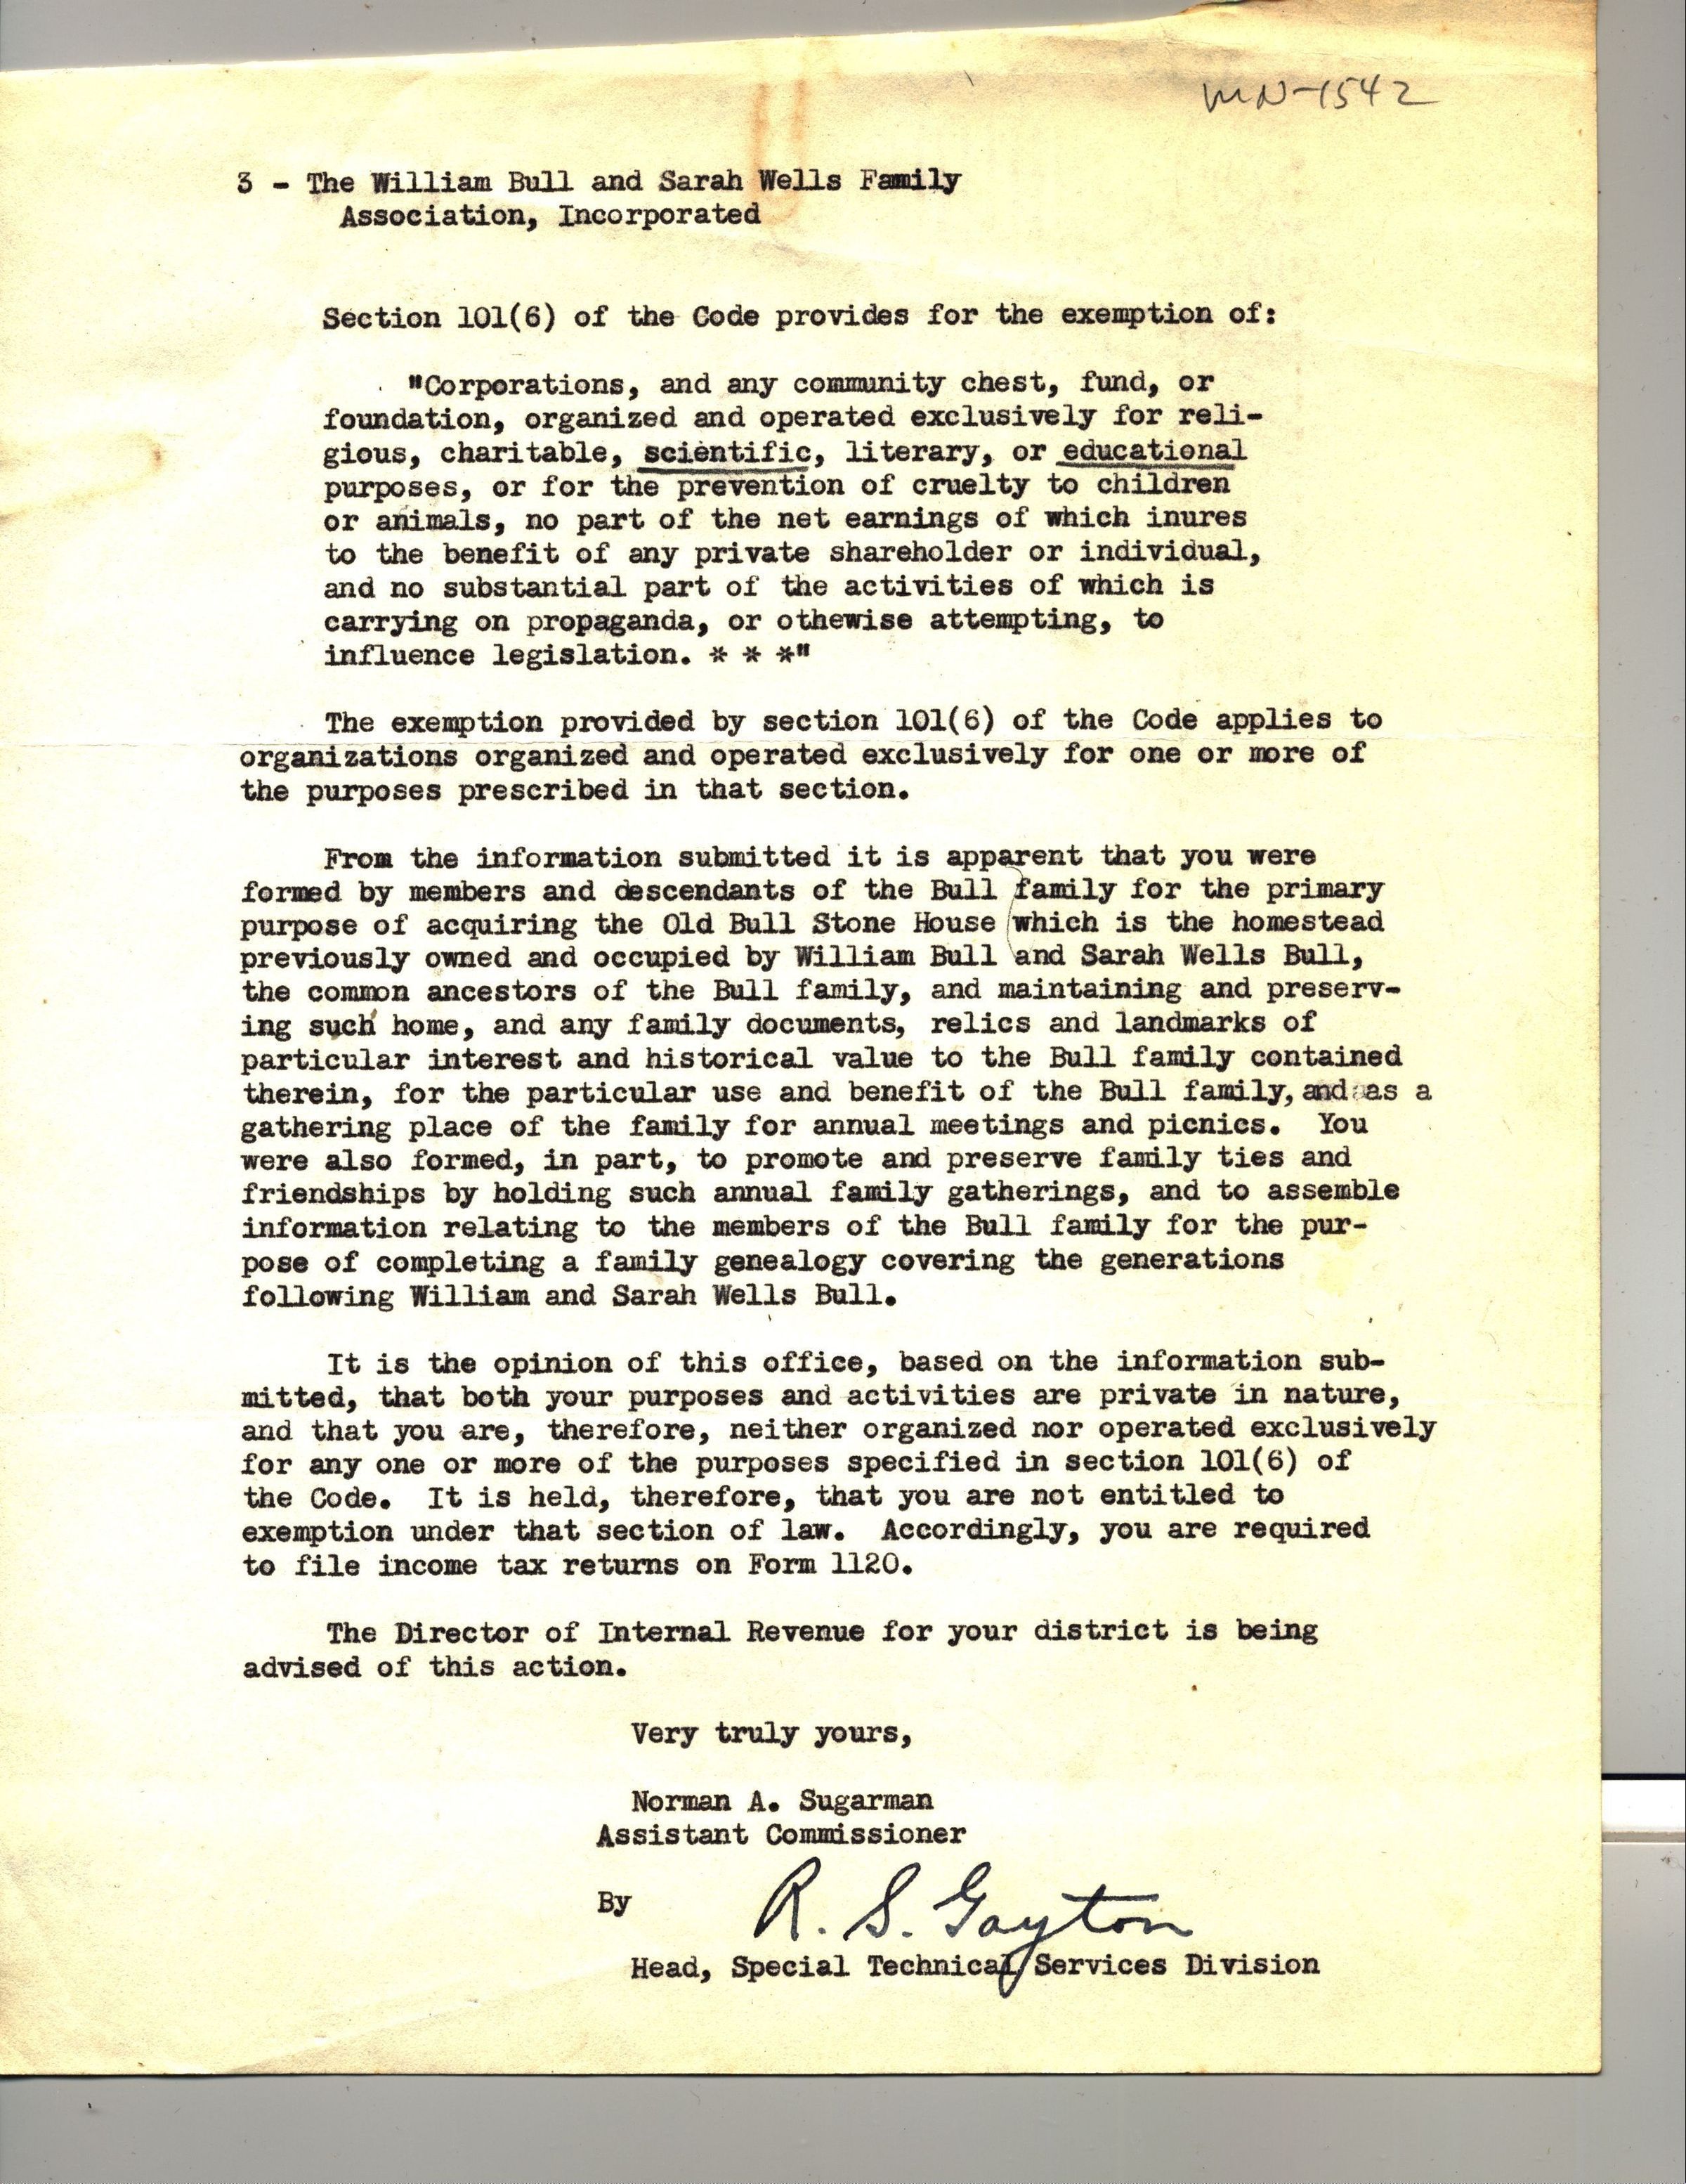
The Treasury Department denied the request for tax exemption. The ruling concluded that:
The Association's purposes and activities are private in nature, specifically for the "particular use and benefit of the Bull family."
Because it serves a private family interest rather than a broad public or charitable one, it does not meet the "exclusive" requirements of Section 101(6).
Consequence: The Association was required to file federal income tax returns using Form 1120.